Key Takeaways
- Record precisely where your money is going before making any changes. It is crucial to gain insight into your spending before constructing a realistic budget.
- Don’t create a budget based on arbitrary rules; instead, base it on your reality. In general, much of the percentage-based guidance isn’t applicable to a genuinely lean income, and the most important things should be prioritised.
- Try various budgeting strategies. There are many budget systems available, such as envelope budgeting, zero-based budgeting, and weekly mini-budgets, to name a few.
- It helps significantly to have small amounts set aside in emergency savings. An adequate buffer, even a simple £100, can appreciably lessen the impact of unexpected costs.
- Take time to reward the progress you make. Acknowledging small successes can keep you motivated when your progress is slower due to a tight budget.
Introduction
I had firsthand experience with budgeting tips that seemed meant for someone with much more disposable income than I had. With pounds already stretched, generic advice such as eating out less or giving up your coffee habit didn’t help much. In this article, I want to share what truly worked for me when I had to learn to budget on a very low income.
The Problem With Old-Fashioned Budgeting Advice
I followed a lot of mainstream budgeting advice before realising it wasn’t working for me. I think it’s worthwhile to explain why, in my opinion, it didn’t work.
Most budgeting tips assume you have money to save, income you are willing to sacrifice, a monthly café habit to break, or extra snacks you can cut back on. When someone earns just enough to pay for basic necessities they already can’t afford, such advice is not only unhelpful but almost insulting.
What also caught my attention was that much of the “budgeting” information focuses on percentages save 20 percent, spend no more than 30 percent on housing, and so on without realising this isn’t realistic for everyone.
If you’re spending half your income on rent, rigid percentage rules can feel like a no-win proposition for reducing that expense it just creates a false sense of disappointment instead. There are a lot of “one-size-fits-all” ideas that I had to unlearn to finally find what worked for me.
The First Step to Understanding Your Money Is to Get a Clear Picture
My first step in changing my spending habits and creating a formal budget was to ensure I knew exactly where my money was going. I wasn’t sure how much clarity this would provide before changing my spending, but tracking alone was enough to make a difference.
For an entire month, I recorded all my expenses coffee, bus fare, snacks from the vending machine, you name it. I didn’t try to alter my spending during this period; I only observed it.
I noticed all sorts of patterns I hadn’t been aware of small items that cost me more than I realised. Most of the time, when I received paycheques, I needed to cover bills, and since they didn’t always fall at the same time each month, it was a source of stress.
I made a complete list of all my fixed costs rent, utilities, minimum debt payments, and monthly bills that remained the same each month. This gave me an accurate starting point in writing, rather than relying on mental approximations.
So there was a ‘face reality’ phase, which meant aligning my total fixed costs with my actual take-home pay. As many of us with restricted budgets know, there is little real flexibility once necessities are accounted for.
But instead of feeling defeated by this, I chose to view it as valuable information and the clear picture I needed for real progress, rather than operating on autopilot, making guesses, and hoping things would resolve themselves.
Creating a Budget Based on Reality, Not Ideals
After knowing where my money was going, I began creating a budget based on the reality of my situation, not what I thought a “responsible” budget should be. This change helped me see whether I could follow through.
I started by putting money towards my true bills, and the absolute necessity items were my housing, utilities, food, work transportation, and minimum debt payments.
While this may seem obvious, I had been using basic, “one-size-fits-all” budget guides that suggested allocating money to “entertainment” before I could even afford rent. As a result, my budget didn’t make sense for my situation and caused unnecessary anxiety.
I also gave up on imposing myself on these random percentage “rules”. Changing my savings percentage wasn’t a good idea, since the amount I would be saving wasn’t feasible given my income. Start by saving whatever you can; it is better than aiming for an unattainable savings target and then stopping altogether.
It was also imperative to incorporate a category for unexpected expenses into the budget. Oftentimes, tight budgets are not due to poor planning but to life events such as illnesses, car repairs, medical copays, and other unforeseen costs.
When those direct costs arose, even setting aside five or ten pounds a week made things easier than having to scramble when an unplanned expense occurred.
Deciding on a Budgeting Method That Works for You
I can’t remember how many budgeting systems I tried and struggled with before I found one I liked, instead of just practising what I heard was the “latest or greatest” budgeting system.
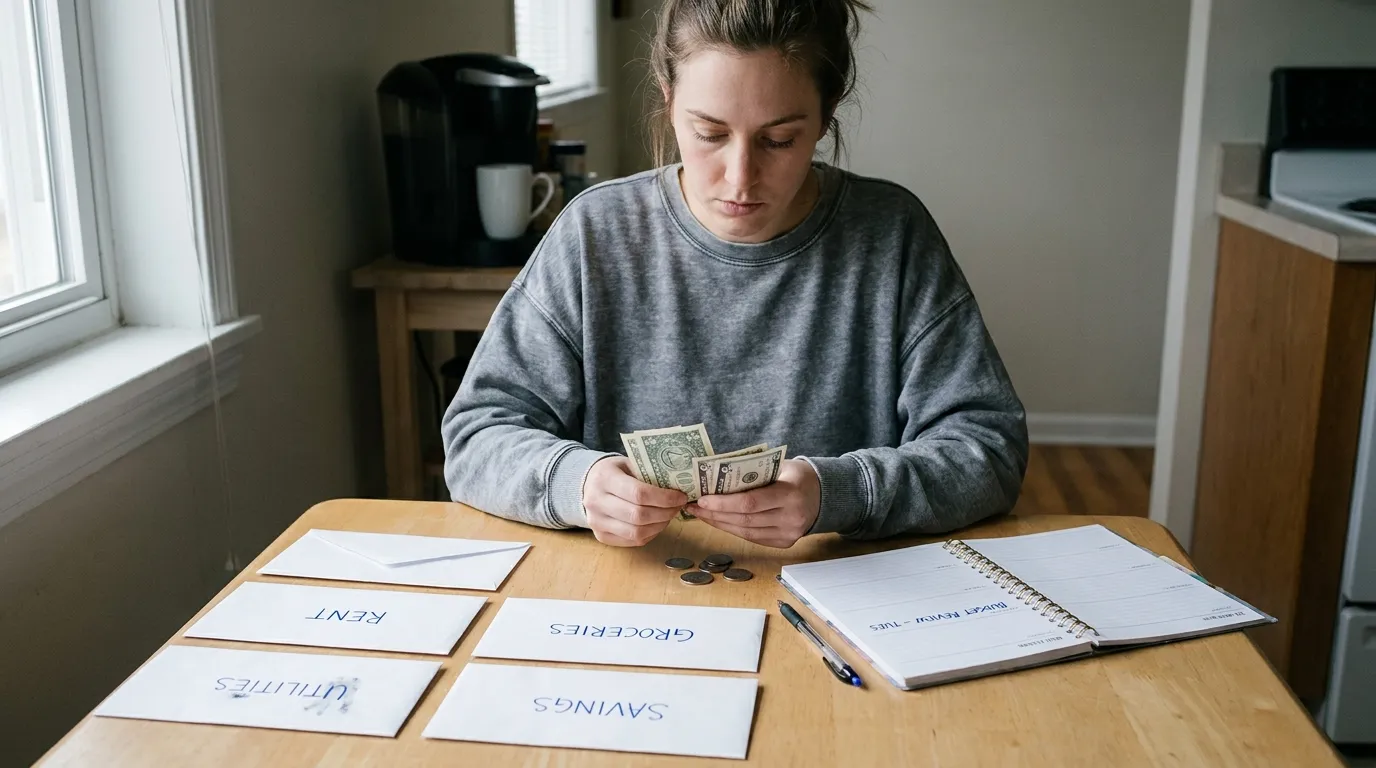
What worked surprisingly well for me was the envelope method, which involves physically or virtually separating money into envelopes for each spending category. You only spend what is allotted to each envelope. The day of the week when the funds ran out for groceries or petrol was a stark reality and was easier for me to grasp than numbers on a spreadsheet.
I eventually switched to a digital version of this system, using separate savings sub-accounts, which was as good as or better than carrying cash, without the hassles.
I also tried a zero-based budget, where every pound is allocated to a specific expense or savings goal before the month begins. This approach created intentionality and helped eliminate the “where did my money go?” feeling at the end of each pay period.
I settled on a basic mix, putting the set costs first and then taking the remaining small flexible income and spending it out of an envelope. If you’re just beginning, I suggest trying a few different techniques for several weeks before deciding which one works best for you.
Budget-Friendly Budgeting Methods to Try — for beginners!
In case you still don’t know where to begin, check out a handful of easy techniques that you can try:
- Envelope system: Assign budgets or ‘envelopes’ to specific spending categories. When an envelope is depleted, you stop spending in that category for the rest of the period.
- Zero budgeting: Before the month starts, assign every pound of income to a purpose, such as spending, bills, or savings.
- Pay yourself first method: Schedule regular savings, even if it’s a small amount, and make it happen before other payments.
- Needs and everything else: If categorising every expense seems daunting, start by dividing your budget into just two categories: needs and everything else.
- Weekly mini-budgets: Divide your budget into smaller, more manageable weekly budgets, which may be better for a small or fluctuating income.
I tried out some of these strategies for a couple of weeks at a time and then ultimately discovered which system really took away the finance strain in my life, instead of making it even more complicated.
Making More Money Without Spreading Yourself Too Thin
Spending less is important, but I found that if you’re on a low income, there is only so much fat you can remove before you reach the point of what you really need. Audit trail also became a critical component of my income journey, so how to get more income, no matter how small, was a key element in my finances.
I wanted to get started, so I sought out something I had to do anyway, but could add to my profits on top, without too much extra time or effort; otherwise, I ran a risk of burnout, and I didn’t think I could add to my load. It was a good one-time injection of cash – just getting rid of stuff I didn’t need in my house.
I also considered more flexible part-time positions to accommodate my current lifestyle, instead of enforcing an inflexible, typical 9-to-5 job, which would only cause more stress. A few extra hours a week, applied consistently to a financial objective, made a difference over the months!
That said, I believe that it is important to be forthright – this isn’t always feasible or right away depending on a person’s situation, health, caring needs, or opportunities in the community. If this is one method of staying lean and healthy that you’re not able to do at this moment, I don’t think you should feel like a failure.
It’s important to focus on what really is achievable for you, whether it’s managing your expenses, improving your income, or getting more awareness about your finances, rather than forcing yourself into measures that do not make real sense to your lifestyle.
Creating an Emergency Fund – Even with a Little One
I used to consider emergency funds as belonging to individuals with lots of room in their spending plan. Yet, I currently feel that even having a small emergency savings account is among the most beneficial tools in the wallet of individuals stuck with a tight budget, particularly since unexpected expenses hit tight budgets the hardest.
When I embarked on this journey, I told myself that my initial target would be only one hundred pounds, as I felt that was manageable from the beginning, unlike the thousands of pounds that most advice suggests. That smaller (but still realistic) accomplishment made me feel accomplished and inspired me to continue, instead of feeling disheartened for not reaching my target.
By automating these small and regular transfers, even £5 per paycheque, into a separate savings account, I eliminated the temptation not to save when it gets tight in the purse strings. Since it was not enough to influence my spending, I hardly felt its loss, but it continued to grow over the years.
Even though it was only a small amount, the way I managed it changed how I dealt with unexpected expenses. I’d never had a car repair or medical bill crash my budget; instead, I had some space to absorb the shock, and that meant I wasn’t as stressed, yet the fund was still relatively small.
When Your Progress Seems Slow, How To Keep Going
Working with a limited income, it was easy to become discouraged when that income didn’t increase as rapidly as I would’ve liked. It was important to me to find ways to stay focused when my progress was slow and stick to my budget long-term.
I began to recognise the small victories that could lead to progress over time, not just major achievements. When I managed to maintain my grocery budget for an entire week and save a bit for my savings account, or for a small purchase, I felt good about it and didn’t push those accomplishments aside, instead thinking of them as steps, no matter how small.
It’s also been a big help for me to think about why I’m budgeting, be it to alleviate financial strain, to save for something I want, or just to feel more in control of my situation. When days were discouraging, it was on these motivations that I found myself returning to get a feel for what is driving me and what got me started.
Putting in the time to connect, be present, and do what matters along the way. Here are a couple of small success points I had to learn to accept and cheer on instead of write off:
- Keeping track of your spending for a week without making any changes yet, but you have done it successfully!
- Importance of sticking to the grocery budget, no matter what creative methods or menu changes were suggested to do so.
- Hitting the milestones of £50 or £100, whatever the time to reach there.
- Not taking on additional debt when hit by an unplanned expense, including a cut to spending or using savings.
- Staying within the budget system for one month without dropping it totally, but without wheedling around.
Noticing those smaller accomplishments kept me focused on what I was doing when the larger monetary goals were still a long way off.
Summary
This starts from the ground, using realistic expectations, honest tracking and flexibility – not percentages and strict rules – to reach a realistic budget, given one’s net income level.
What I did notice as a big difference for me was that I was not in a situation where I had to restrict my spending as much as possible; I was trying to be clear and focus on what was intentional, know where my money was going, and make the most informed decision I could make in a genuinely limited situation.
If you are just getting started, I would say give yourself the same advice I give myself: Be patient with yourself in your progress; celebrate what small steps you can do; and create a system that works for your life, which may not align with the best financial advice.